A motorcycle or scooter remains one of the most practical purchases for Indian commuters. It can shorten a journey to work, help a student reach college, or make deliveries possible for a small business. But rising prices, insurance premiums and registration charges mean even an everyday two-wheeler can require a sizeable amount upfront. Bike loans spread that cost across monthly instalments instead of consuming all available savings.
The tempting part of two-wheeler finance is a small down payment or an instant approval at the showroom. Neither proves that a loan is economical. Finance companies and banks may calculate or display interest differently, and a borrower can end up paying significant processing, documentation, collection and foreclosure charges. The best offer balances the actual on-road price, a realistic down payment and a repayment period that does not squeeze ordinary living expenses.
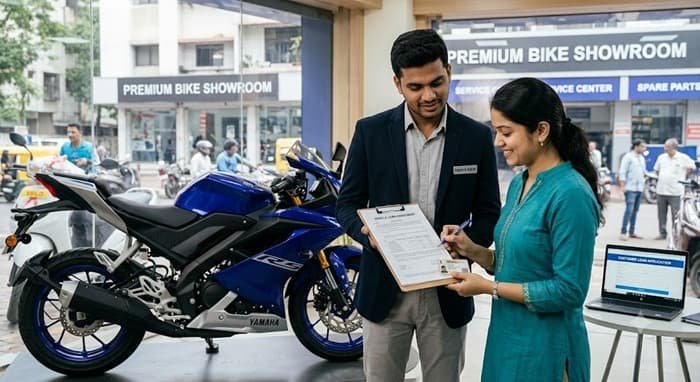
This 2026 guide includes verified bank and non-banking finance products for regular bikes, scooters and, where offered, electric or premium motorcycles. The order is an editorial shortlist, not a claim that one provider has the lowest rate for everyone. Now, let’s check out the top 10 two-wheeler loan providers in India for 2026.
What to Check Before Financing a Bike or Scooter
Down payment: Check whether the lender finances the on-road price or only the vehicle price and whether a zero-down-payment offer applies to your model.
Real borrowing cost: Ask if interest is flat or reducing balance, and get the annual percentage rate or complete EMI and fee schedule.
Loan closure: Review late-payment fees, bundled insurance, prepayment charges and the procedure for removing hypothecation from the registration certificate.
Top Two-Wheeler Loan Providers in India
1. HDFC Bank Two-Wheeler Loan
HDFC Bank provides regular bike, electric two-wheeler and superbike financing, with digital applications and pre-approved offers for selected customers. Its published material describes terms up to 48 months on ordinary two-wheelers and potentially full funding for eligible customers and models. Instant disbursal claims apply to qualifying cases, not every application. Examine the final rate, processing charges and whether a down payment is still required.
Best for: Existing bank customers checking pre-approved showroom finance.
2. ICICI Bank Two-Wheeler Loan
ICICI Bank offers standard, digital and electric two-wheeler financing. Its product pages indicate potential funding up to the full on-road price and tenures up to 36 months on the standard loan, subject to eligibility. The digital journey can include e-signing and dealer payment. Buyers of expensive bikes should confirm loan-size eligibility rather than assuming all scooters and premium models receive identical terms.
Best for: Customers comfortable with an app-led borrowing process.
3. Axis Bank Two-Wheeler Loan
Axis Bank finances scooters, motorcycles and electric two-wheelers and runs a separate superbike offer. Published terms include tenures of 12–48 months for standard bikes and up to 60 months for superbikes, with possible full on-road funding. The bank advertises a rate concession for qualifying electric two-wheelers. Review the applicable vehicle classification because a high-capacity bike may need the premium loan product.
Best for: Borrowers considering both regular bikes and premium motorcycles.
4. IDFC FIRST Bank Two-Wheeler Loan
IDFC FIRST Bank supports new two-wheelers, including electric vehicles, with up to 95% financing and tenures extending to 60 months in eligible cases. It also provides separate financing for used bikes. Its published rate methodology identifies reducing-balance interest, making the cost easier to compare with other reducing-balance offers. Ask about the actual processing fee and the final rate by vehicle category.
Best for: Buyers who want a reducing-balance quotation and used-bike options.
5. Bajaj Finance Two-Wheeler Loan
Bajaj Finance advertises loans from ₹35,000 to ₹21 lakh, with tenures between six and 84 months and possible full on-road funding for eligible buyers. Applications can begin online and continue through partner dealerships. The wide range is useful for ordinary scooters and high-value motorcycles, but borrowers should not overlook processing charges, bounce fees and early-closure costs.
Best for: Customers comparing wide tenure choices and dealer availability.
6. Hero FinCorp Two-Wheeler Loan
Hero FinCorp offers dealer-linked and digital finance for new bikes and scooters, advertising loans up to ₹3.5 lakh and funding up to 95% of vehicle cost. Repayment may extend to 60 months, depending on the offer. Its practical appeal lies in access to finance at dealerships and relatively straightforward documentation. Verify whether insurance, accessories or other products have been added to the sanctioned principal.
Best for: Daily commuters seeking conventional dealership-based finance.
7. TVS Credit Two-Wheeler Loan
TVS Credit provides two-wheeler loans for salaried and self-employed buyers, with published funding of up to 95% of on-road price and terms reaching 60 months for eligible cases. It offers dealership assistance and digital service channels. Some promotional fast approvals depend on successful verification, so they should not be treated as guaranteed disbursal. Request a complete breakdown of documentation and collection fees.
Best for: Buyers seeking a broad showroom finance network.
8. Shriram Finance Two-Wheeler Loan
Shriram Finance offers loans for new bikes and scooters and also discusses used two-wheeler finance. It advertises funding up to 95% of on-road price and repayment over 12–60 months, subject to approval. The product is relevant to salaried and self-employed customers, including some borrowers outside major cities. Check down payment, processing fees and any minimum holding period before the loan can be foreclosed.
Best for: Semi-urban and self-employed applicants comparing dealer finance.
9. Tata Capital Two-Wheeler Loan
Tata Capital finances commuter motorcycles, scooters and higher-value bikes, with tenures of six to 60 months. Its main product page describes loan amounts up to ₹10 lakh, while some premium-segment material gives different ceilings; eligibility should be checked for the chosen vehicle. Crucially, certain advertised rates are described as flat rates, which require conversion before comparison with a reducing-balance bank quote.
Best for: Buyers considering premium models and flexible loan tenures.
10. State Bank of India (SBI) Two-Wheeler Loan
SBI has a specific two-wheeler loan scheme for eligible purchases and a separate Super Bike Loan for higher-value motorcycles. Its published loan information distinguishes ordinary two-wheelers from more expensive models and describes an electric-vehicle concession in specified cases. Eligibility, loan ceiling and processing fees differ by scheme. Check the category first: a standard bike buyer should not assume the superbike terms apply.
Best for: Bank-focused buyers who prefer clearly differentiated bike-loan products.
Two-Wheeler Loan Rates and Total Cost
Bike loan pricing varies markedly with the model, amount financed, credit history, down payment and tenure. Do not compare an NBFC flat rate with a bank reducing-balance rate as though the percentages were equivalent. Ask every lender for total interest, all upfront fees, EMI dates, bounced-payment charges, optional insurance costs and the amount payable on foreclosure. A promotional zero-down-payment deal can still be relatively expensive over time.
How to Pick a Practical Two-Wheeler Loan
- Calculate the full on-road bill: Include registration, compulsory insurance, road tax and any genuine optional equipment.
- Get two comparable quotations: Request a bank and a finance-company offer for the same principal and term, showing total rupees payable.
- Avoid unnecessary add-ons: Ask whether extended warranties, accident covers or dealer extras are optional and whether financed amounts attract interest.
- Keep a cash buffer: Leave money for fuel or charging, service visits, tyres and unexpected repairs; never choose an EMI based on salary alone.
Conclusion
A two-wheeler loan should make commuting easier, not turn a modest purchase into expensive debt. Compare real total cost, margin money and closure conditions, and treat quick approvals and low headline rates as starting points rather than final answers.
FAQs
Q. Can I buy a bike with zero down payment in India?
Some lenders advertise up to 100% of the on-road price for eligible models and borrowers. That is not guaranteed approval. Ask for the written dealer settlement, including registration, insurance, fees and what you must pay at delivery.
Q. Why can a 12% flat bike-loan rate cost more than a 14% reducing-balance rate?
Under a flat calculation, interest may be charged against the original principal for the full term. Under reducing balance, interest is charged on the declining outstanding amount. Compare APR or the total repayment in rupees, not the printed rates alone.
Q. Can someone with no previous credit history get a two-wheeler loan?
Sometimes. Some lenders accept first-time borrowers after assessing income, residence stability, the chosen model and down payment. Approval may require a co-applicant or higher margin. A pre-approved message from a dealer is not the final loan sanction.
Q. Are electric scooters eligible for different loan terms?
Many lenders offer EV finance and some advertise a small rate concession. Confirm that the specific model, battery ownership arrangement and dealer are approved. Also ask whether battery subscriptions are included in the financed price.
Q. What documents do I need after paying off a bike loan?
Obtain a no-objection certificate and Form 35 or other documentation required for termination of hypothecation, then complete the relevant RTO or Parivahan process. Keep proof of zero balance and check that the registration record no longer lists the lender.